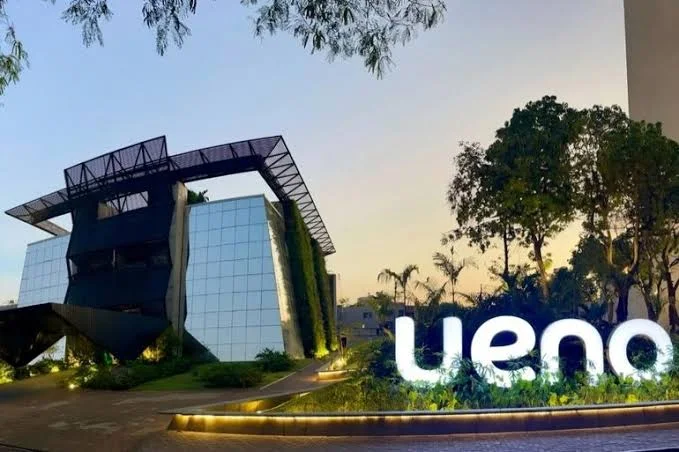
Paraguay's banking sector has been rocked by the collapse of Ueno Bank after regulators uncovered Sh18.83 billion in loans extended to three companies connected to the lender's controlling shareholders, exposing serious failures in financial reporting, lending practices and regulatory compliance that left the institution facing a major capital crisis.
The Central Bank of Paraguay ordered the bank's resolution on November 2, 2026, after a review of its financial records revealed that its capital ratio had dropped to less than half the minimum level required by law.
Ueno was among Paraguay's leading digital banking institutions, with a customer base of nearly three million people. It offered a range of financial services, including savings deposits and loans, making it an important player in the country's banking industry.
The lender obtained its banking licence in 2023 before expanding its operations through the acquisition of Visión Banco in 2024. The deal accelerated its growth and increased its reach in the country's financial market.
By June 2026, Ueno had reported assets valued at Sh541.8 billion, customer deposits of Sh361.2 billion and loans totalling Sh322.5 billion, figures that reflected the institution's substantial presence before its collapse.
However, an examination of its lending activities revealed transactions involving businesses associated with the bank's controlling shareholders, raising questions about whether the institution had followed the rules governing loans to related parties.
An internal supervisory report reviewed by ABC Color revealed that Ueno had issued loans worth approximately Sh18.83 billion to three companies linked to its controlling shareholders between September 2025 and May 2026.
By April 2026, the companies owed the bank Sh15.87 billion, an amount that exceeded the permitted lending limit for related parties by Sh5.29 billion. The regulatory ceiling stood at Sh10.58 billion.
Related-party lending refers to loans issued by a bank to individuals or businesses connected to its owners, directors or senior management. Such transactions are subject to strict limits to prevent conflicts of interest, excessive lending to connected businesses and the misuse of customers' deposits for the benefit of shareholders.
In Ueno's case, the transactions raised concerns about the bank's exposure to businesses associated with its owners and whether the loans had been properly disclosed and managed.
The concerns were compounded by problems involving the quality of its loan portfolio and gaps in financial records, further exposing weaknesses in the institution's internal controls.
Despite the growing concerns, Ueno had maintained that it was meeting regulatory requirements and had attempted to address its financial difficulties through a Sh12.9 billion capital injection plan announced on October 29, just four days before the central bank stepped in.
The proposed funding was, however, insufficient to prevent the intervention after a review of the bank's financial statements exposed a much larger capital deficit than previously reported.
The institution suffered another setback on November 5 when credit rating agency FIX downgraded it from AA-py to Dpy. The agency cited the undisclosed loans to shareholder-linked companies, poor loan quality and inadequate financial documentation among the reasons for the downgrade.
The bank's failure has also raised concerns over the safety of the billions of shillings deposited by customers and public institutions, particularly given the substantial amounts held by government agencies.
Government institutions accounted for Sh106.68 billion of Ueno's total deposits, with Paraguay's social security institution alone holding Sh38.06 billion in the bank.
The central bank's intervention disrupted customers' access to their accounts and raised concerns about the availability of public funds held by the institution.
Investors and creditors were also affected after the resolution process suspended payments on Ueno's debt securities. These included obligations linked to an international bond worth Sh45.15 billion that the bank issued in March 2026.
The financial scandal has since spread into Paraguay's political and legal circles, with prosecutors charging 27 bank officials and associates over the developments.
The crisis has also triggered impeachment proceedings against President Santiago Peña, who previously had business interests connected to the group controlling Ueno.
As authorities work to manage the bank's collapse, the central bank has started the process of compensating eligible depositors through the country's deposit guarantee scheme.
The initial payments cover customers with deposits of up to Sh206,400, provided they do not have outstanding loans with Ueno and hold an active account with another financial institution.
Under the statutory protection framework, each depositor is entitled to coverage of up to Sh4.902 million as regulators process the remaining claims.
Ueno's collapse has brought attention to the financial dangers of undisclosed lending to businesses linked to bank owners, excessive exposure to related parties and weak financial reporting.
The case also demonstrates how a financial institution can report billions of shillings in assets and experience rapid customer growth while serious weaknesses in its lending practices and financial controls threaten its ability to remain solvent.