Borrowers who have ended up paying several times the amount they originally borrowed are at the centre of a parliamentary investigation, with lawmakers preparing to question asset finance companies over allegations of excessive interest, undisclosed loan terms and questionable debt recovery practices.
The National Assembly’s Finance and National Planning Committee has received 110 complaints against lenders accused of imposing charges that push repayment amounts to between two and four times the original loans, raising fresh concerns about the cost of credit and the protection available to borrowers in Kenya.
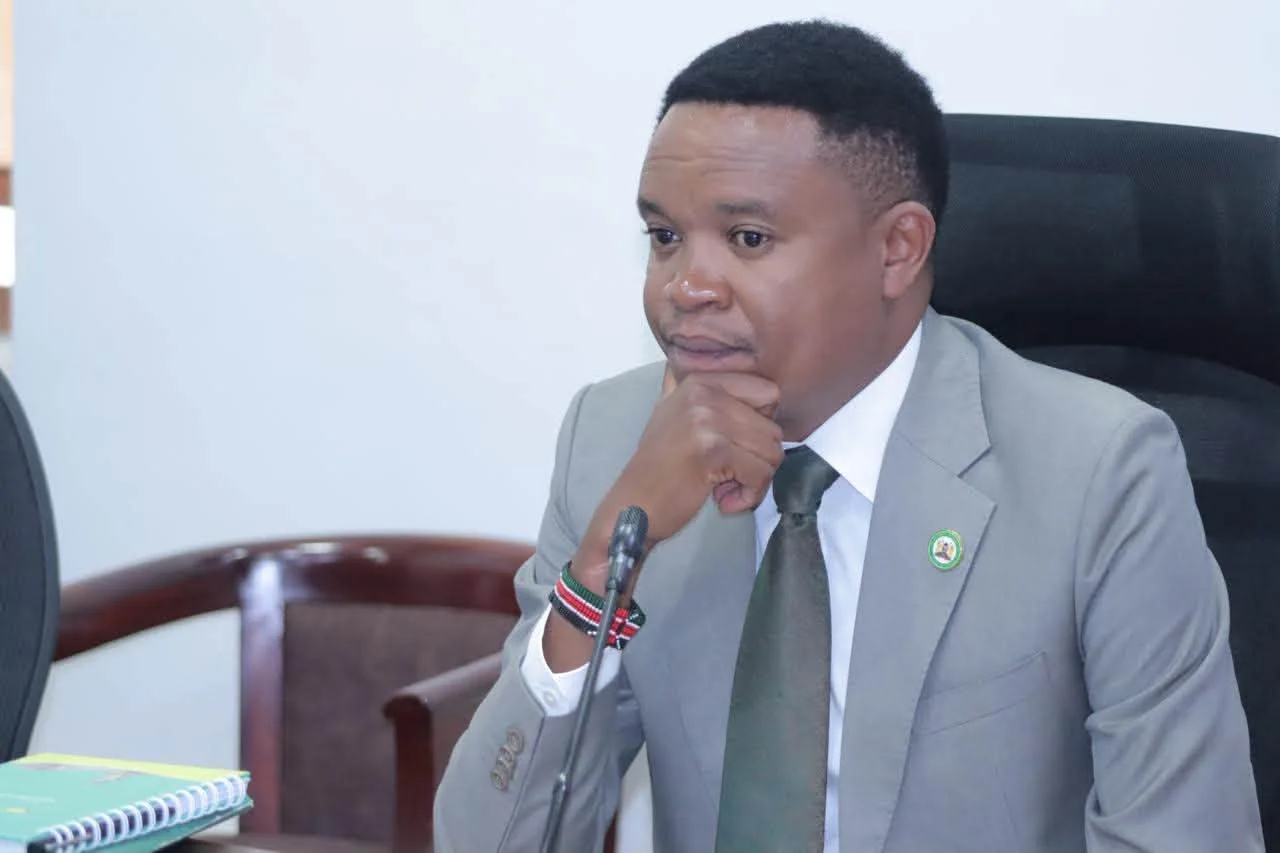
Committee chairperson Kimani Kuria said the complaints had continued to reach lawmakers during an ongoing inquiry into lending practices, prompting the team to summon the companies named in a petition submitted by boda boda riders.
The lenders are expected to appear before the committee on November 5 to respond to the allegations and explain how their financing arrangements comply with existing laws.
Kuria said some borrowers had reportedly paid far more than the amounts they initially received, while others claimed they were not given clear information about the loans they were taking.
“We have continuously, since the start of this inquiry, received numerous other complaints where there is no disclosure of the loan amount, and some customers have paid even three or four times the loan amount,” Kuria said.
The committee is seeking explanations from the companies over the alleged charges and the information provided to customers before they enter into financing agreements.
Kuria warned that lenders who fail to attend the scheduled meeting could face formal summons under Standing Order 191 of the National Assembly, signalling the committee’s intention to ensure that the companies answer questions about their practices.
The investigation comes as lawmakers examine whether existing regulations are being followed by credit providers, particularly companies offering loans and asset financing outside the traditional banking sector.
The Business Laws (Amendment) Act, 2024, brought previously unregulated non-deposit-taking credit providers under the regulatory oversight of the Central Bank of Kenya (CBK), strengthening the framework governing their operations.
Kuria said the changes were intended to improve supervision of non-bank lenders and prevent borrowers from being subjected to costly credit arrangements that leave them struggling to clear their debts.
One of the safeguards highlighted during the inquiry is the in-duplum rule, which limits the interest recoverable on qualifying non-performing loans to the outstanding principal amount when a loan becomes non-performing.
The principle is intended to prevent interest from accumulating indefinitely on loans that have fallen into default, protecting borrowers from repayment obligations that continue to grow long after they stop servicing their debts.
However, the committee says it continues to receive complaints alleging that some lenders charge interest and other amounts far beyond the original sums borrowed, raising questions about compliance with the rules and the effectiveness of consumer protection measures.
The lawmakers want the affected companies to explain their lending practices and demonstrate that their charges and recovery procedures fall within the applicable legal framework.
Hidden loan terms and repossessions under scrutiny
Excessive interest charges are not the only concern facing the committee. Lawmakers are also investigating allegations that some lenders fail to provide borrowers with adequate information about the amounts borrowed and the terms attached to their credit agreements.
The disclosure of loan amounts and repayment conditions is a key area of concern because customers need to understand their financial obligations before committing to financing arrangements.
The committee is also examining complaints involving the repossession of financed assets, particularly allegations that property is taken from borrowers without proper notice or compliance with the required procedures.
Such practices can leave customers facing growing repayment obligations while also losing assets they depend on to earn an income.
Asset financing plays an important role for small businesses and workers in the informal sector, including boda boda operators who rely on loans to acquire motorcycles and other income-generating equipment.
For these borrowers, the terms attached to a financing agreement can directly affect their daily earnings, their ability to meet repayment schedules and their capacity to sustain their businesses.
Lawmakers are therefore seeking to establish whether the concerns raised by borrowers point to failures in how some companies disclose loan terms, calculate charges or enforce repayment agreements.
The November 5 meeting is expected to give the committee an opportunity to hear from the lenders named in the petition as it works towards completing its inquiry.
Kuria said the committee intends to conclude its investigations and present a report to the National Assembly, which could pave the way for legal or regulatory action if violations are established.
The inquiry will give lawmakers an opportunity to assess the complaints received, examine the conduct of the companies involved and determine whether the existing safeguards are sufficient to protect borrowers.
Kuria maintained that lenders must operate within the law and should not impose financing arrangements that violate the rules governing the credit market.
“No lender should be allowed in Kenya to lend beyond or outside the legal framework,” he said.
The committee's findings could inform decisions on how alleged breaches should be addressed, although any further action will depend on the evidence gathered and the outcome of the inquiry.
The parliamentary probe comes amid wider concerns about the treatment of borrowers by digital credit providers and weaknesses in the safeguards governing the sector.
In July 2026, the Competition Authority of Kenya warned that gaps in the legal framework governing digital lenders were exposing borrowers to hidden fees, predatory lending and coercive debt recovery practices.
The warning added to concerns about whether customers have adequate protection against unfair lending terms and aggressive methods used to recover unpaid debts.
As the committee pursues its inquiry, lawmakers are seeking answers from the affected asset finance companies on the complaints received and their compliance with existing requirements.
The investigation will also help the House assess whether further legal or regulatory measures are necessary to address the reported problems and strengthen protections for people seeking credit.